Revenue leakage is the gap between the work your field service business completes and the revenue it legitimately captures. It is not always fraud or a dramatic accounting error. More often, it is a missed material, an approved change that never reaches the invoice, a discount without an owner, or a completed job that waits too long to bill.
The best way to find leakage is to follow one job through the entire revenue path: customer request, estimate, scheduled work, completed work, invoice, and payment. If the record changes at any handoff, the business needs a control.
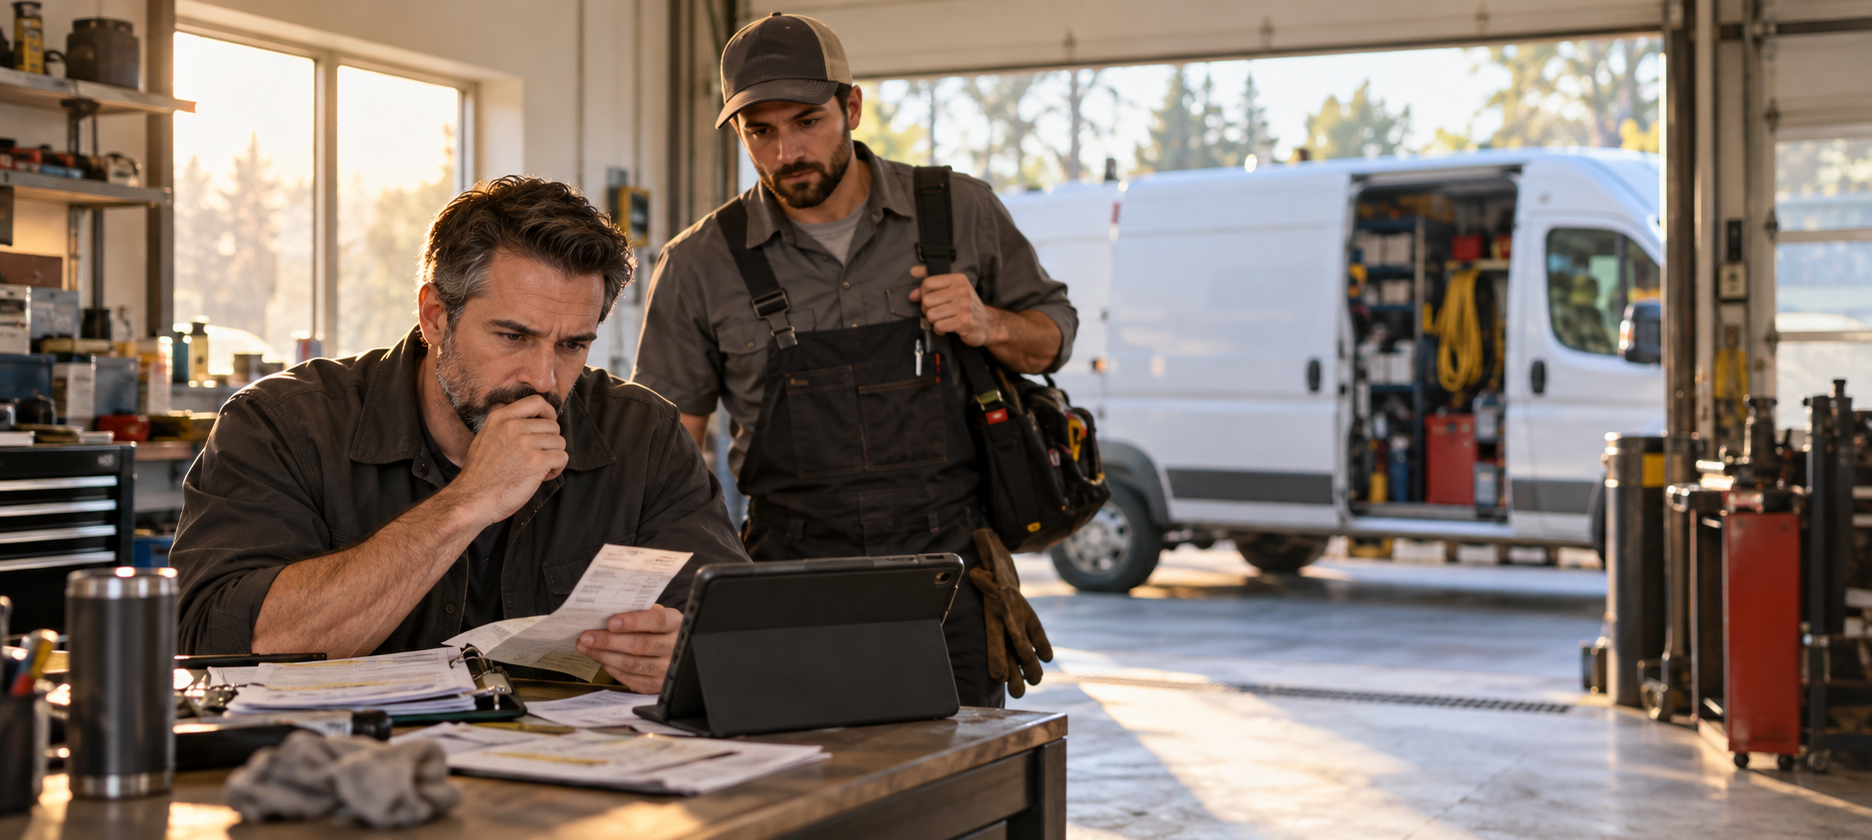
Hook visual. Revenue leakage usually appears in the handoffs between completed work, documentation, invoicing, and payment—not as one dramatic accounting error.
For the broader scorecard that connects revenue leakage with profitability, productivity, and cash flow, see the Fielddio guide to assessing field service business performance.
The 7 most common leakage points
1. Materials used but not billed
Technicians may use fittings, filters, wire, fasteners, chemicals, or other consumables without adding them to the job record. The amount may seem small on one visit, but repeated omissions reduce job margin over an entire month.
The control is simple: require materials to be recorded before the job is closed. If your team uses a standard truck-stock list, distinguish replenishment from materials consumed on a customer job. Review exceptions rather than asking technicians to remember every item after the fact.
2. Approved changes that disappear
Scope changes are a frequent source of leakage in installation, remodeling, landscaping, and larger maintenance work. A customer approves extra labor or materials, but the approval remains in a text message, email, or technician note instead of becoming a billable line item.
Use one change-order record with the approved amount, approval date, customer authorization, and billing status. The job is not financially complete until the change is either invoiced or explicitly marked non-billable with a reason.
3. Completed work waiting to be invoiced
Every day between completion and invoicing creates an opportunity for information to be lost. A missed invoice also delays collections and makes the current month look weaker than the work performed.
Track the median number of days from job completion to invoice date. Set an internal service-level target that fits your workflow, then investigate jobs outside the target. The goal is not to rush inaccurate invoices; it is to remove avoidable waiting.
4. Uncontrolled discounts and write-offs
Discounts can be appropriate for warranty work, service recovery, promotions, or strategic accounts. The risk appears when the reason is not recorded or the same discount is used inconsistently.
Require a reason code and an approver for discounts above a defined threshold. Review total discounts as a percentage of invoiced revenue and inspect the largest individual adjustments. A discount is not automatically leakage, but an unexplained discount is an exception worth investigating.
5. Travel, minimum charges, and after-hours fees omitted
Businesses often price the core service correctly but forget visit fees, minimum charges, emergency premiums, disposal fees, or after-hours rates. Make these rules visible in estimates and job templates. The customer should understand what is billable before the work begins.
6. Warranty and callback work misclassified
A legitimate warranty visit should not be billed as new customer work. At the same time, a new issue should not automatically be absorbed as warranty labor. Misclassification can create customer friction and distort technician and job profitability reports.
Record the callback reason, original job, and commercial treatment. When patterns repeat, the underlying issue may be estimating, parts quality, training, or scope—not just billing.
7. Receivables without a follow-up owner
An invoice is not collected revenue. Assign an owner and next action to overdue balances. Keep invoice date, due date, payment date, and dispute status visible in one report.
Cash and accrual accounting can place invoices and payments in different periods, so the business should monitor both invoiced revenue and collected cash. The IRS explanation of accounting methods provides the accounting context; it does not replace a practical collections process.
A weekly revenue leakage audit
Choose a fixed sample, such as every job completed in the prior week or the last 20 completed jobs. Reconcile these five stages:
- The scheduled scope and estimate.
- The actual work and materials recorded.
- Customer approvals and changes.
- The invoice sent.
- The payment received or follow-up action assigned.
For every difference, classify it as captured, legitimately non-billable, pending documentation, disputed, or missed. This classification prevents the team from treating every variance as an error while still making unexplained gaps visible.
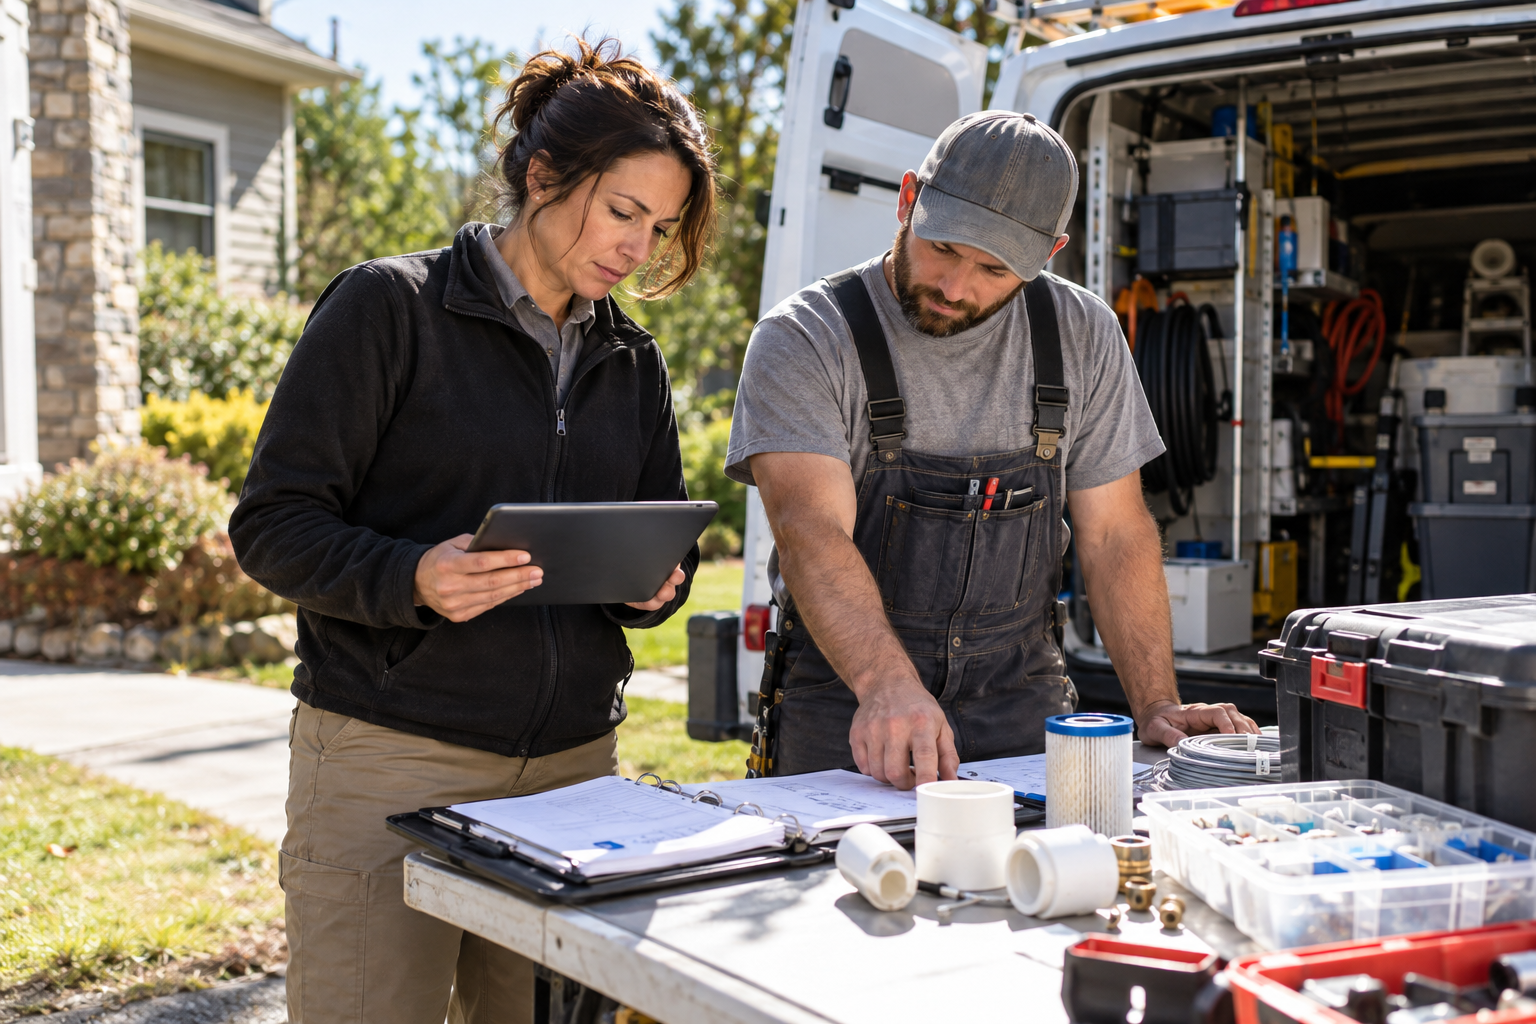
Audit visual. Comparing the work completed, materials used, approvals, invoice, and payment makes the exact handoff requiring attention easier to see.
A simple leakage calculation
Suppose 50 jobs were completed in a month. Eight invoices omitted an average of $35 in legitimately billable materials. Potential missed billing is:
8 × $35 = $280
This is an illustrative control calculation, not a forecast or industry benchmark. Confirm the contract, estimate, and customer authorization before correcting an invoice. The objective is accurate billing, not aggressive billing.
Metrics that show whether the fix worked
Track a small set of before-and-after measures:
- Completed jobs with an invoice attached.
- Median completion-to-invoice delay.
- Materials recorded versus materials purchased or replenished.
- Discount and write-off value by reason.
- Overdue invoice value and next-action coverage.
- Gross profit margin by service type.
Review the measures over the same period and preserve their definitions. The BDC gross profit margin formula is useful for consistency, but there is no universal margin target that applies to every trade or service mix.
Control visual. A short weekly review gives each exception an owner, a next action, and a clear path toward accurate collected revenue.
The practical takeaway
Revenue leakage is best treated as a process-quality problem. Start with one handoff, document the expected record, assign an owner, and review exceptions every week. Once the control works manually, software can reduce duplicate entry and make missing steps easier to see.
Use the Fielddio field service business performance assessment to place leakage in context with job profitability, technician productivity, and cash flow. This article links to the pillar for the complete framework and does not require the pillar to link back to it.
Sources
- IRS Publication 334 — accounting methods and business expenses.
- BDC: Gross profit margin ratio — gross margin formula and interpretation.
This post contains affiliate links. If you make a purchase through these links, we may earn a commission at no extra cost to you.