Is Your Field Service Business Actually Performing Well?
A field service business is performing well when it consistently converts booked work into collected revenue, completes jobs efficiently, protects profit margins, and has enough cash to operate without constant firefighting. Revenue growth alone cannot tell you whether the business is healthy. A company can book more jobs while losing money through callbacks, underpriced work, unbilled materials, or slow collections.
For a small HVAC, plumbing, electrical, cleaning, landscaping, or painting company, the best assessment starts with a handful of numbers you can review every week. You do not need a complex dashboard to begin. You need consistent definitions, accurate job records, and a habit of acting on what the numbers reveal.
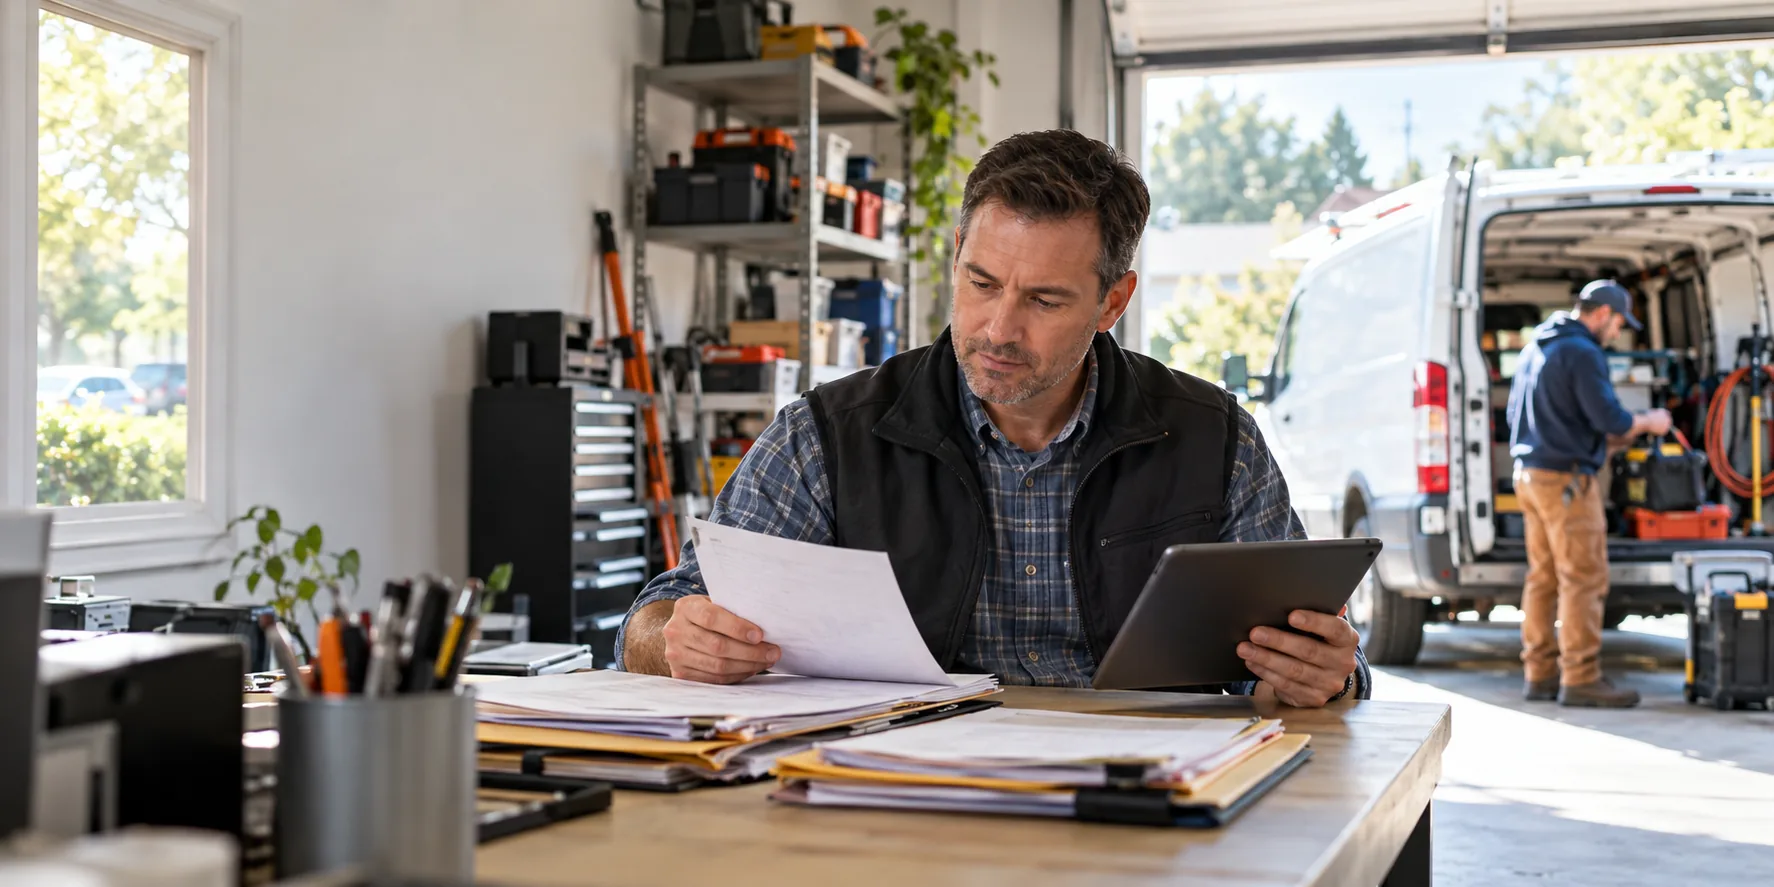
Hook visual. The central question is not whether the business is busy; it is whether completed work becomes profitable, collected revenue with a reliable operating process.
Start With a Simple Business Performance Scorecard
Track these measures for the same period, ideally the last 30 days, and compare them with your own prior periods.
| Measure | How to calculate it | What it tells you |
|---|---|---|
| Lead-to-booking rate | Booked jobs ÷ qualified leads × 100 | Whether inquiries turn into scheduled work |
| Job completion rate | Completed jobs ÷ scheduled jobs × 100 | Whether scheduling and capacity are realistic |
| Revenue per completed job | Revenue on a consistent invoicing or collection basis ÷ completed jobs | How much value each completed visit generates |
| Gross profit margin | (Revenue − direct job costs) ÷ revenue × 100 | Whether pricing covers labor, materials, and other direct costs |
| Operating profit margin | Operating profit ÷ revenue × 100 | Whether the business remains profitable after operating overhead |
| Billable utilization | Billable technician hours ÷ available working hours × 100 | How much technician capacity produces billable work |
| Callback rate | Jobs requiring a return visit for a problem ÷ completed jobs × 100 | Potential quality or diagnostic issues |
| Invoice collection time | Average days from invoice date to payment date | How quickly completed work becomes cash |
Important: Decide what counts as a “job,” “qualified lead,” “direct cost,” and “callback” before comparing results. A consistent, imperfect measure is more useful than a metric that changes definition every week.
Want to see your own baseline? Complete the free Fielddio Business Assessment to measure operational gaps, revenue opportunity, business recovery potential, and the priorities to address first. You receive a free assessment report based on the information you provide.
Step 1: Understand Job Profitability Before Looking at Total Revenue
Job profitability measures how much a specific job contributes after its direct costs. It exposes work that looks busy or high-value but contributes little to the business.
Consider an illustrative plumbing repair:
| Item | Amount |
|---|---|
| Customer invoice | $650 |
| Technician labor, including applicable burden | $180 |
| Parts and consumables | $145 |
| Job-specific travel and disposal | $45 |
| Gross profit | $280 |
| Gross profit margin | 43.1% |
Calculation: ($650 − $180 − $145 − $45) ÷ $650 × 100 = 43.1%.
That $280 is not the owner’s take-home profit. It must still help pay rent, insurance, office staff, software, marketing, vehicles, and other operating expenses not already assigned to the job.
Review job margins by service type, not only company-wide. A high-revenue installation category may produce weaker margins than smaller recurring maintenance jobs. Compare like with like: emergency work, maintenance contracts, and installation projects have different cost structures.
Which costs belong in your calculation?
Include wages and payroll burden attributable to the job, materials, subcontractors, and other directly attributable costs. Treat overhead consistently. If you allocate truck or shop expenses to each job, do not count the same expense again when calculating operating profit.
There is no universal “good” contractor profit margin. Targets depend on trade, market, labor model, service mix, and accounting treatment. Establish your baseline first, then investigate persistent deterioration.
For the accounting definitions behind this section, see the IRS explanation of accounting methods and business expenses and the BDC definition of gross profit margin. Those sources support the formulas; they do not establish a universal target margin for every service trade.
Step 2: Measure Technician Productivity Without Rewarding Rushed Work
Technician productivity is not simply the number of jobs completed. A technician who closes six rushed jobs and generates three callbacks may create less value than someone who completes four jobs correctly.
Useful measures include:
- Billable utilization: billable hours divided by available working hours.
- First-visit completion rate: jobs completed without an avoidable return visit divided by completed jobs.
- Revenue per field hour: collected or invoiced job revenue divided by field hours, using the same basis every time.
- Callback rate: avoidable returns divided by completed jobs.
Example: A technician has 40 available hours and records 26 billable hours. Billable utilization is 26 ÷ 40 × 100 = 65%. The remaining 14 hours are not automatically wasted: they may include travel, training, vehicle preparation, meetings, or unavoidable gaps. The question is whether those hours are necessary, excessive, or preventable.
Do not rank technicians on one metric. Review productivity alongside safety, customer outcomes, job complexity, and workmanship quality.
Step 3: Find Revenue Leakage Between the Job and the Bank
Revenue leakage occurs when a business earns or could legitimately bill for work but fails to capture, invoice, or collect the full amount. In a small service company, the leaks are often ordinary process failures rather than dramatic fraud.
Check for:
- Materials used on site but omitted from invoices.
- Approved change orders that never reach billing.
- Completed jobs waiting several days to be invoiced.
- Discounts issued without a documented reason.
- Unpaid invoices with no follow-up owner.
- Warranty or callback work incorrectly classified as billable—or the reverse.
An illustrative audit of 50 completed jobs finds eight invoices missing an average of $35 in legitimately billable materials. Potential missed billing is 8 × $35 = $280. Confirm contract terms and customer authorization before issuing corrections; not every cost is billable.
A practical weekly control is to reconcile completed jobs → documented work and materials → invoices sent → payments received. Every unexplained gap deserves an owner and a resolution date.
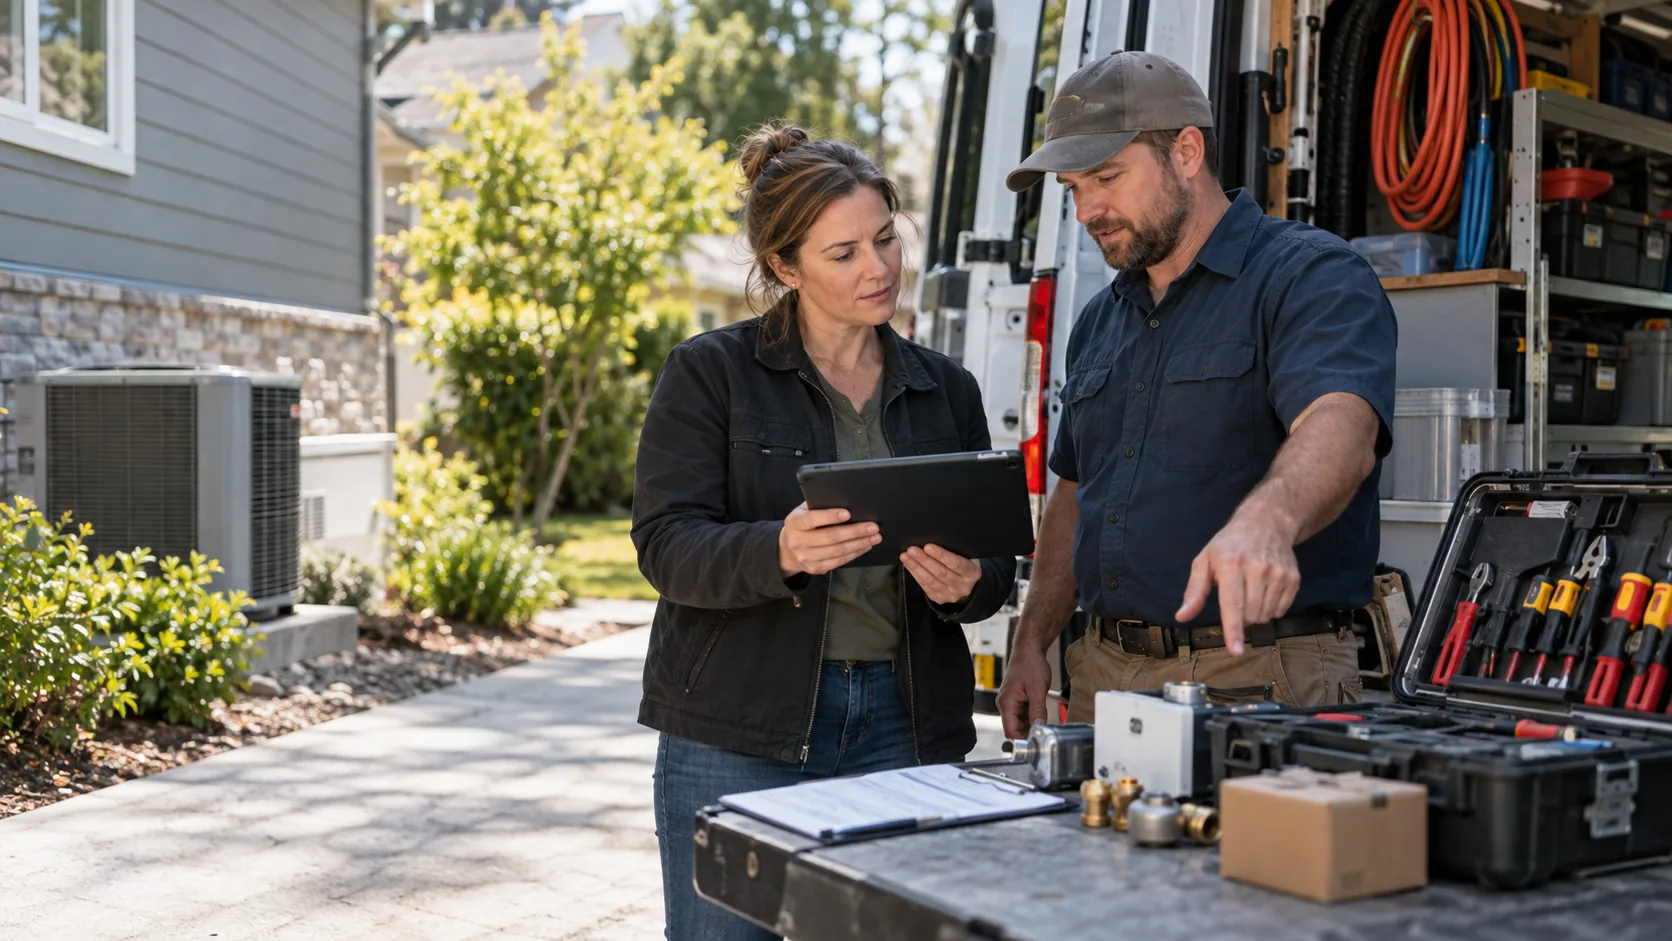
Mid-article visual. Strong performance measurement connects the job record, the technician’s time, the materials used, the invoice, and the customer outcome.
Step 4: Diagnose Hidden Operational Problems
Financial reports often reveal symptoms, not causes. If gross margin declines, the cause might be pricing, supplier costs, excess travel, inaccurate estimates, callbacks, or poor scheduling.
Use this diagnostic table to connect symptoms to the next question:
| Symptom | Possible cause | First check |
|---|---|---|
| Revenue rises but profit falls | Higher direct costs or discounting | Margin by job type |
| Technicians work late but jobs stay unfinished | Scheduling or scope issues | Estimated vs. actual hours |
| Many calls but few booked jobs | Missed calls or weak follow-up | Lead response and booking records |
| Strong sales but weak cash balance | Late invoicing or collections | Invoice aging and payment dates |
| Repeat visits increase | Parts readiness or quality problems | Callback reasons by job category |
Avoid changing pricing, staffing, and marketing simultaneously. Investigate one material issue at a time so you can tell whether the change helped.
Step 5: Separate Profit From Cash Flow
A profitable business can still struggle to pay its bills. Profit recognizes revenue and expenses under an accounting method; cash flow tracks money entering and leaving the bank.
The IRS overview of cash and accrual accounting explains why an invoice and a bank receipt may fall in different periods. The SBA break-even guide is useful when separating fixed costs, variable costs, and contribution margin. Use those concepts to interpret the scorecard; do not substitute a break-even calculation for job-level costing.
For example, you may invoice $20,000 this month but collect only $13,000 while payroll and suppliers require immediate payment. The gap is a working-capital problem even if the invoices are expected to be paid.
At least weekly, review your bank balance, upcoming payroll and taxes, overdue receivables, supplier obligations, and expected collections. Ask your bookkeeper or accountant to help distinguish operating cash flow from owner withdrawals, debt payments, and one-time purchases.
Step 6: Run a 30-Minute Weekly Review
A short, repeatable meeting is more useful than a sophisticated report nobody opens.
First 10 minutes — results: Review completed jobs, billed revenue, collected cash, gross margin, callbacks, and open invoices.
Next 10 minutes — exceptions: Identify the three largest deviations from your recent baseline. Inspect actual job records instead of guessing.
Final 10 minutes — actions: Assign one owner, one deadline, and one measurable outcome to each priority. For example: “By Friday, reconcile every completed job older than 48 hours without an invoice.”
Keep the scorecard simple enough to maintain even when the owner is busy in the field.
Build a Practical 90-Day Improvement Plan
| Period | Priority | Deliverable |
|---|---|---|
| Days 1–30 | Establish trustworthy numbers | Consistent job-costing, invoicing, and scorecard definitions |
| Days 31–60 | Fix the largest measurable leak | One tested workflow change with a named owner |
| Days 61–90 | Standardize and review | Documented process and before/after comparison |
Closing visual. The goal is a measured improvement plan that the owner and field team can actually maintain.
Example: If invoices routinely go out five days after job completion, test a same-day closeout checklist. Compare the median invoicing delay before and after the change. A shorter delay is useful evidence, but do not claim it increased profit unless collections or other outcomes support that conclusion.
When Should You Consider Field Service Software?
Spreadsheets and a disciplined weekly review can work for a very small team. Software becomes worth evaluating when job records, technician schedules, estimates, change orders, and invoices regularly fall out of sync.
Before paying for a tool, list the process failures you need it to solve. Check whether the system supports your trade, mobile field workflows, customer communication, integrations, and exportable job-level reporting. Request a trial with your own sample workflow, and compare total costs—including setup and training—against the expected operational benefit.
The goal is not to buy more software. It is to create a reliable path from customer inquiry to completed job, accurate invoice, and collected payment.
Your Next Step: Diagnose, Measure, Improve
Start with your last 20 completed jobs. For each, record the quoted price, final invoice, direct labor and materials, completion date, callback status, and payment status. Calculate gross margin and note missing information.
You will quickly see which problem to investigate first: estimating, productivity, billing, quality, or collections. Use that baseline to choose one improvement for the next 30 days and measure its effect.
Fielddio’s approach: Diagnose. Measure. Improve. The strongest business performance system is the one you can actually maintain.
Ready for a personalized diagnosis? Start the free Fielddio Business Assessment and receive your assessment report.
Sources and definitions
- IRS Publication 334 — accounting methods, business income, expenses, and cost of goods sold.
- BDC: Gross profit margin ratio — gross profit margin definition and formula.
- BDC: Operating profit margin — operating profit margin definition and formula.
- SBA: Break-even point — fixed costs, variable costs, and contribution margin.
All dollar examples in this article are hypothetical. They illustrate the arithmetic only and are not industry-wide benchmarks. For an existing Fielddio hub on software selection, see Field Service Management Software. This pillar intentionally does not link to the five satellite articles.
This post contains affiliate links. If you make a purchase through these links, we may earn a commission at no extra cost to you.
2 thoughts on “How to Assess Your Field Service Business Performance”